Roth vs. Traditional IRAs: Best for 2026 Retirement Goals?
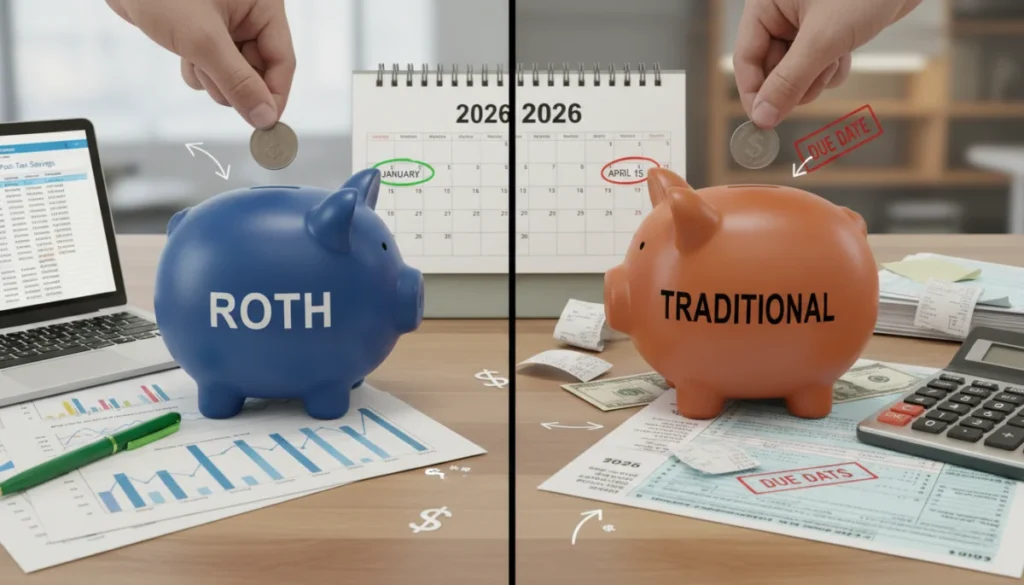
Comparing Roth vs. Traditional IRAs: Which Personal Finance Option is Best for Your 2026 Retirement Goals? hinges on understanding their distinct tax treatments and how they align with your anticipated financial future.
As you plan for your financial future, one of the most critical decisions involves selecting the right retirement savings vehicle. For many, this choice comes down to Comparing Roth vs. Traditional IRAs: Which Personal Finance Option is Best for Your 2026 Retirement Goals? Understanding the fundamental differences between these two popular individual retirement arrangements is essential for maximizing your savings and minimizing your tax burden in retirement. This article will break down the intricacies of each, helping you navigate this pivotal financial decision.
Understanding Traditional IRAs: Tax-Deferred Growth
Traditional IRAs have been a cornerstone of retirement planning for decades, primarily due to their tax-deferred growth benefits. Contributions to a Traditional IRA are often tax-deductible in the year they are made, which can lead to an immediate tax break. This means that the money you contribute reduces your taxable income for that year.
The beauty of a Traditional IRA lies in its tax deferral. Your investments grow over time, and you don’t pay taxes on those gains until you start withdrawing funds in retirement. This compounding effect, unburdened by annual taxes, can significantly boost your retirement nest egg. However, all qualified withdrawals in retirement are taxed as ordinary income.
Contribution Limits and Deductibility
For 2026, the IRS sets specific limits on how much you can contribute to a Traditional IRA. These limits are typically adjusted for inflation annually. Eligibility to deduct your contributions depends on several factors, including whether you or your spouse are covered by a retirement plan at work and your modified adjusted gross income (MAGI).
- Contribution Limits: Stay updated on the IRS annual limits, as they can change.
- MAGI Phase-Outs: If you’re covered by a workplace plan, your deduction might be phased out at higher income levels.
- Non-Deductible Contributions: If you can’t deduct your contributions, you can still contribute to a Traditional IRA, but you’ll pay taxes on the earnings in retirement.
Understanding these limits and deductibility rules is crucial for optimizing your tax strategy. It’s not just about contributing; it’s about contributing smartly to maximize your current and future tax advantages.
Withdrawal Rules and Required Minimum Distributions (RMDs)
Withdrawing funds from a Traditional IRA typically begins in retirement, usually after age 59½. Withdrawals before this age may be subject to a 10% penalty, in addition to being taxed as ordinary income, unless an exception applies. A key aspect of Traditional IRAs is the concept of Required Minimum Distributions (RMDs).
RMDs mandate that you begin withdrawing a certain amount from your Traditional IRA once you reach a specific age, currently 73. These distributions are fully taxable. Failing to take an RMD can result in significant penalties, highlighting the importance of understanding and adhering to these rules as you approach retirement age. The RMD age has been increasing, so it’s vital to stay informed on the latest regulations.
In summary, Traditional IRAs offer immediate tax deductions and tax-deferred growth, with taxes paid upon withdrawal in retirement. This structure is particularly appealing if you anticipate being in a lower tax bracket during retirement than you are during your working years.
Exploring Roth IRAs: Tax-Free Withdrawals in Retirement
Roth IRAs present a compelling alternative to Traditional IRAs, especially for those who foresee themselves in a higher tax bracket in retirement. The primary advantage of a Roth IRA is that qualified withdrawals in retirement are entirely tax-free. This means that all the growth your investments experience over decades can be accessed without paying a single cent in taxes, a powerful benefit.
Unlike Traditional IRAs, contributions to a Roth IRA are made with after-tax dollars, meaning there’s no upfront tax deduction. However, this upfront tax payment paves the way for tax-free income in your golden years, offering significant peace of mind and predictable retirement income. This can be a game-changer for long-term financial planning.
Contribution Eligibility and Income Limits
While Roth IRAs offer attractive tax benefits, there are income limitations that determine who can contribute directly. For 2026, these modified adjusted gross income (MAGI) limits are likely to be adjusted for inflation, but they typically restrict high-income earners from direct contributions. If your income exceeds these thresholds, you might still be able to contribute through a strategy known as the “backdoor Roth IRA.”
- MAGI Limits: Be aware of the annual income thresholds that affect your eligibility for direct Roth contributions.
- Backdoor Roth: This strategy involves contributing to a non-deductible Traditional IRA and then converting it to a Roth IRA.
- Spousal Contributions: Even if you don’t have earned income, your spouse might be able to contribute to a Roth IRA on your behalf.
Navigating these eligibility rules is crucial. If direct contributions aren’t possible, exploring alternatives like the backdoor Roth can still provide access to these valuable tax-free retirement funds.
Withdrawal Rules and No Required Minimum Distributions
The withdrawal rules for Roth IRAs are generally more flexible than those for Traditional IRAs. Qualified withdrawals are tax-free and penalty-free, provided you meet two conditions: you’ve had the Roth IRA for at least five years, and you’re age 59½ or older, disabled, or using the funds for a qualified first-time home purchase (up to $10,000).
One of the most appealing features of a Roth IRA is the absence of Required Minimum Distributions (RMDs) for the original owner. This means you can leave your money in your Roth IRA for as long as you wish, allowing it to continue growing tax-free for your entire lifetime. This flexibility makes Roth IRAs excellent estate planning tools, as beneficiaries can inherit the account and potentially continue its tax-free growth.
In essence, Roth IRAs offer tax-free growth and tax-free withdrawals in retirement, with no RMDs for the original owner. This structure is particularly advantageous if you anticipate being in a higher tax bracket in retirement or desire greater flexibility with your retirement funds.
Key Differences: Taxes Now vs. Taxes Later
The core distinction between Traditional and Roth IRAs boils down to when you pay taxes. With a Traditional IRA, you generally get a tax deduction for your contributions in the present, and your withdrawals are taxed in retirement. This is the “taxes later” approach. Conversely, with a Roth IRA, you contribute after-tax dollars, meaning no upfront deduction, but your qualified withdrawals in retirement are tax-free. This is the “taxes now” strategy.
Your choice should largely depend on your current income tax bracket compared to your anticipated tax bracket in retirement. If you expect to be in a higher tax bracket later in life, a Roth IRA might be more beneficial. If you believe your tax bracket will be lower in retirement, a Traditional IRA could offer greater tax savings.
Tax Deductibility and Tax-Free Growth
The immediate impact of your IRA choice is on your current tax bill. Traditional IRA contributions can reduce your taxable income for the year, potentially lowering your current tax liability. This can be a significant advantage, especially for those in higher income tax brackets during their working years.
On the other hand, Roth IRA contributions do not offer an upfront tax deduction. However, the long-term benefit of tax-free growth and withdrawals can far outweigh the lack of an immediate tax break, especially if your investments perform well over several decades. The power of tax-free compounding is immense.
Flexibility and RMDs
Another crucial difference lies in the flexibility of withdrawals and the presence of RMDs. Traditional IRAs are subject to RMDs, forcing you to withdraw funds and pay taxes on them once you reach a certain age. This can sometimes disrupt careful financial planning, especially if you don’t immediately need the income.
Roth IRAs, for the original owner, are not subject to RMDs. This provides unparalleled flexibility, allowing your money to continue growing tax-free for as long as you live. This feature also makes Roth IRAs an attractive option for estate planning, as they can be passed on to beneficiaries who can continue to benefit from the tax-free growth.
Ultimately, the decision rests on your individual circumstances and future tax predictions. Both options offer significant advantages, but their benefits are realized at different stages of your financial journey.
Factors to Consider for Your 2026 Retirement Goals
When deciding between a Roth and Traditional IRA for your 2026 retirement goals, several personal factors come into play. It’s not a one-size-fits-all decision; what works best for one person might not be ideal for another. Carefully evaluating your current situation and future expectations is key to making an informed choice.
Consider your current income, your expected income trajectory, and your anticipated tax bracket in retirement. These elements will heavily influence which IRA type provides the most significant long-term financial advantage. Think about your entire financial picture, not just isolated components.
Current vs. Future Tax Bracket
Perhaps the most significant factor is your comparison of your current tax bracket to your projected tax bracket in retirement. If you are currently in a high tax bracket and expect to be in a lower one in retirement, a Traditional IRA’s upfront deduction might be more appealing. This allows you to pay taxes when your income is lower.
Conversely, if you are currently in a lower tax bracket and anticipate a higher tax bracket in retirement (perhaps due to increased earnings or other retirement income sources), a Roth IRA could be more advantageous. Paying taxes now at a lower rate to enjoy tax-free withdrawals later can be a powerful strategy.
Age and Time Horizon
Your age and how long you have until retirement also play a crucial role. If you are young and have many years until retirement, the tax-free growth of a Roth IRA can be incredibly powerful. The longer your money has to grow tax-free, the more significant the benefit.
- Early Career: Roth IRAs often make sense for younger individuals in lower tax brackets.
- Mid-Career: A mix of both or a strategic conversion might be beneficial as income rises.
- Nearing Retirement: Traditional IRAs might be favored if you anticipate a significant drop in income during retirement.
The time horizon allows for greater compounding, and tax-free growth can lead to a substantially larger nest egg. For those closer to retirement, the immediate tax deduction of a Traditional IRA might offer more tangible short-term benefits.
Considering these factors holistically will guide you toward the IRA option that best supports your unique financial journey and retirement aspirations for 2026 and beyond.
Hybrid Strategies and Conversions
For many individuals, the choice between a Roth and Traditional IRA isn’t an either/or proposition. A hybrid approach, utilizing both types of accounts, can offer the best of both worlds, providing flexibility and optimizing tax advantages across different stages of life. Understanding conversion strategies can further enhance your retirement planning.
Combining both account types can provide a balanced approach to tax planning, allowing you to hedge against future tax rate uncertainties. This strategy offers more control over your taxable income in retirement, which can be a significant advantage.
The Backdoor Roth IRA
For high-income earners who exceed the direct contribution limits for a Roth IRA, the “backdoor Roth IRA” strategy provides a legitimate way to contribute. This involves making a non-deductible contribution to a Traditional IRA and then converting those funds to a Roth IRA. While the initial contribution is not tax-deductible, the conversion allows you to get money into a Roth account.
It’s important to be aware of the “pro-rata rule” if you have existing pre-tax Traditional IRA balances, as this can complicate the tax implications of a backdoor Roth. Consulting a financial advisor is highly recommended to navigate this strategy effectively and avoid unintended tax consequences.
Roth Conversions from Traditional IRAs
Another powerful strategy is converting funds from an existing Traditional IRA to a Roth IRA. This is known as a Roth conversion. When you perform a Roth conversion, you pay taxes on the converted amount in the year of the conversion. This can be a smart move if you anticipate being in a higher tax bracket in retirement than you are currently.
- Taxable Event: Conversions are taxable in the year they occur.
- Future Tax-Free Growth: Once converted, the funds grow tax-free and are withdrawn tax-free in retirement (assuming qualified withdrawals).
- Strategic Timing: Consider converting during years when your income is lower, or tax rates are generally favorable.
Roth conversions can be particularly beneficial during periods of lower income or when tax rates are temporarily low, allowing you to lock in future tax-free income. This strategy requires careful planning and an understanding of the tax implications.
By understanding and potentially employing these hybrid strategies and conversion options, you can create a more robust and tax-efficient retirement plan, adapting to your evolving financial situation and future tax landscape.
Beyond IRAs: Other Retirement Savings Vehicles
While Traditional and Roth IRAs are excellent tools for individual retirement savings, they are just two pieces of a larger financial puzzle. For a truly comprehensive retirement plan, it’s wise to consider other available savings vehicles, particularly those offered through employers. Diversifying your retirement savings across different account types can provide additional flexibility and tax advantages.
A holistic approach to retirement planning involves looking at all your options and how they can collectively work to achieve your financial goals. Each vehicle has its own set of rules and benefits, and understanding them is crucial.
Employer-Sponsored Plans: 401(k)s and 403(b)s
Many employers offer retirement plans such as 401(k)s (for for-profit companies) or 403(b)s (for non-profit organizations and educational institutions). These plans often come with higher contribution limits than IRAs and may include employer matching contributions, which is essentially free money for your retirement.
Like Traditional IRAs, contributions to most 401(k)s and 403(b)s are tax-deferred, meaning you contribute pre-tax dollars, and your investments grow tax-deferred until withdrawal. Many of these plans also offer a Roth option, allowing for after-tax contributions and tax-free withdrawals in retirement, similar to a Roth IRA.
Health Savings Accounts (HSAs) for Retirement Healthcare
Often overlooked as a retirement savings tool, a Health Savings Account (HSA) can be incredibly powerful, especially for healthcare costs in retirement. To contribute to an HSA, you must be enrolled in a high-deductible health plan (HDHP).
- Triple Tax Advantage: Contributions are tax-deductible, investments grow tax-free, and qualified withdrawals for medical expenses are tax-free.
- Retirement Healthcare: After age 65, you can withdraw HSA funds for any purpose without penalty, though non-medical withdrawals will be taxed as ordinary income.
- Investment Potential: Many HSAs allow you to invest funds once a certain balance is reached, providing another avenue for tax-advantaged growth.
HSAs offer a unique “triple tax advantage” that makes them an attractive component of a well-rounded retirement strategy. They can serve as a dedicated fund for healthcare expenses, which often become a significant cost in retirement.
By integrating various savings vehicles into your retirement strategy, you can build a more resilient and tax-efficient financial future, ensuring you’re prepared for whatever comes your way.
Making Your Decision for 2026: A Personalized Approach
The decision of whether a Roth or Traditional IRA is best for your 2026 retirement goals is deeply personal and depends on your unique financial circumstances, income levels, and future expectations. There’s no universal answer, but by carefully evaluating your situation, you can make an informed choice that aligns with your long-term financial well-being.
Consider consulting with a qualified financial advisor to help you analyze your specific situation. They can provide personalized guidance, taking into account all aspects of your financial life and helping you project future tax scenarios.
When a Traditional IRA Might Be Best
A Traditional IRA generally makes sense if you are currently in a high tax bracket and anticipate being in a lower tax bracket during retirement. The immediate tax deduction can provide significant savings now, and you’ll pay taxes on withdrawals when your income (and thus your tax rate) is lower.
It’s also a good choice if you’re looking to reduce your taxable income now to qualify for other tax credits or deductions that have income limitations. The tax-deferred growth is a powerful benefit, allowing your investments to compound without annual tax drag.
When a Roth IRA Might Be Best
A Roth IRA is often the preferred choice if you are currently in a lower tax bracket and expect to be in a higher one in retirement. Paying taxes on your contributions now at a lower rate means your qualified withdrawals in retirement will be completely tax-free, regardless of how much your investments have grown.
Roth IRAs also offer greater flexibility with withdrawals (no RMDs for the original owner) and can be an excellent tool for estate planning. If you value predictable tax-free income in retirement and flexibility, a Roth IRA is a strong contender.
Ultimately, the best approach for Comparing Roth vs. Traditional IRAs: Which Personal Finance Option is Best for Your 2026 Retirement Goals? involves careful consideration of your present and future financial outlook, potentially combining both types of accounts for optimal results. Your financial journey is unique, and your retirement strategy should reflect that.
| Feature | Description |
|---|---|
| Tax Treatment | Traditional: Tax-deductible contributions, taxed withdrawals. Roth: After-tax contributions, tax-free withdrawals. |
| RMDs | Traditional: Required Minimum Distributions apply. Roth: No RMDs for original owner. |
| Income Eligibility | Traditional: No income limits for contributions. Roth: Income limits for direct contributions. |
| Flexibility | Roth offers greater withdrawal flexibility and estate planning benefits. |
Frequently Asked Questions About IRAs
Traditional IRAs offer tax-deductible contributions in the year they are made, potentially lowering your current taxable income. Your investments grow tax-deferred, meaning you don’t pay taxes on earnings until you withdraw them in retirement. This can be advantageous if you expect to be in a lower tax bracket in your golden years.
A Roth IRA is often preferred if you anticipate being in a higher tax bracket during retirement. Contributions are made with after-tax dollars, but qualified withdrawals in retirement are entirely tax-free. This provides predictable tax-free income and eliminates the concern of future tax rate increases on your retirement savings.
For Traditional IRAs, there are no income limits for making contributions, though deductibility may be phased out based on income and workplace retirement plan coverage. Roth IRAs, however, have modified adjusted gross income (MAGI) limits that restrict direct contributions for high-income earners. Backdoor Roth strategies exist for those exceeding limits.
Required Minimum Distributions (RMDs) are mandatory withdrawals you must start taking from Traditional IRAs (and most employer-sponsored plans) once you reach a certain age, currently 73. These distributions are taxable as ordinary income. Roth IRAs, for the original owner, are not subject to RMDs, offering greater flexibility.
Yes, you can contribute to both a Roth and a Traditional IRA. However, the total combined contributions for a given year cannot exceed the annual contribution limit. Many individuals choose to utilize both types of accounts to diversify their tax strategy and benefit from both tax-deferred growth and tax-free withdrawals in retirement.
Conclusion
The choice between a Roth and Traditional IRA for your 2026 retirement goals is a pivotal personal finance decision with long-lasting implications. By understanding the nuances of each – from tax treatment and eligibility to withdrawal rules and RMDs – you can make an informed choice that aligns with your financial outlook. Whether you prioritize immediate tax deductions or future tax-free income, a well-thought-out IRA strategy is fundamental to securing a comfortable retirement. Remember to review your strategy periodically and consider professional financial advice to adapt to changing circumstances and tax laws.
