Credit Card Debt: Pay Off $5,000 in 18 Months
Paying off $5,000 in credit card debt within 18 months demands a strategic personal finance plan, meticulous budgeting, and disciplined adherence to a clear repayment strategy.
Are you grappling with the weight of credit card debt, feeling as though it’s an inescapable burden? Understanding the true cost of credit card debt: how to pay off $5,000 in 18 months with a strategic personal finance plan is not just a financial goal, but a pathway to reclaiming your financial freedom. This comprehensive guide will equip you with practical steps and actionable strategies to systematically tackle your debt and emerge stronger on the other side.
Understanding the True Cost of Credit Card Debt
Credit card debt often seems manageable at first, especially with minimum payment options. However, the cumulative effect of interest, fees, and the opportunity cost of not saving can be staggering. Many individuals underestimate how quickly a seemingly small balance can balloon into a significant financial obstacle, impacting their future goals and overall well-being.
Beyond the principal amount, the true cost includes the interest charged, which can be exceptionally high on credit cards. It also encompasses late payment fees, over-limit fees, and the psychological toll of constant financial stress. This section will delve into these often-overlooked aspects, providing a clear picture of what credit card debt truly costs you.
The compounding effect of interest
One of the most insidious aspects of credit card debt is the compounding interest. When you only make minimum payments, a significant portion of that payment often goes towards interest, leaving very little to reduce the principal balance. This creates a cycle where your debt seems to grow despite your efforts to pay it down.
- High Annual Percentage Rates (APRs): Credit card APRs can range from 15% to over 25%, making even small balances expensive over time.
- Minimum payments trap: Minimum payments are designed to keep you paying for an extended period, maximizing the interest collected by the issuer.
- Opportunity cost: Money spent on interest could have been invested, saved, or used for other important financial goals.
Understanding these costs is the first critical step towards motivating yourself to tackle your credit card debt head-on. Recognizing the long-term implications will fuel your commitment to a strategic repayment plan.
Assessing Your Current Financial Situation
Before you can effectively pay off $5,000 in credit card debt, you need a clear and honest assessment of your current financial standing. This involves a detailed look at your income, expenses, and existing debts. Without this foundational understanding, any repayment strategy will be built on shaky ground and less likely to succeed.
Gather all your financial statements, including credit card bills, bank statements, and any other loan documents. This step is crucial for identifying where your money is going and where adjustments can be made. It’s about creating a transparent view of your financial landscape.
Calculating your net income
Your net income is what you bring home after taxes and other deductions. This is the amount you have available to cover your expenses and allocate towards debt repayment. Be precise in this calculation, as it will form the basis of your budget.
Tracking your expenses diligently
Many people are surprised to learn how much they spend on non-essential items. Tracking every dollar for a month or two can reveal spending patterns and areas where you can cut back. Use budgeting apps, spreadsheets, or even a simple notebook to record all your outflows.
- Fixed expenses: Rent/mortgage, loan payments, insurance premiums.
- Variable expenses: Groceries, dining out, entertainment, transportation.
- Discretionary spending: Subscriptions, impulse purchases, hobbies.
By meticulously assessing your financial situation, you gain the clarity needed to formulate a realistic and effective debt repayment plan. This initial effort will pay dividends in your journey towards financial freedom.
Crafting Your Strategic Personal Finance Plan
With a clear understanding of your financial situation, it’s time to craft a strategic personal finance plan designed to tackle your $5,000 credit card debt within 18 months. This plan will serve as your roadmap, guiding your financial decisions and ensuring you stay on track. It’s about setting realistic goals and implementing actionable steps to achieve them.
A well-structured plan involves more than just making payments; it encompasses budgeting, identifying areas for savings, and potentially increasing income. The key is consistency and commitment to the strategies you establish. This section will walk you through the essential components of such a plan.
Establishing a realistic budget
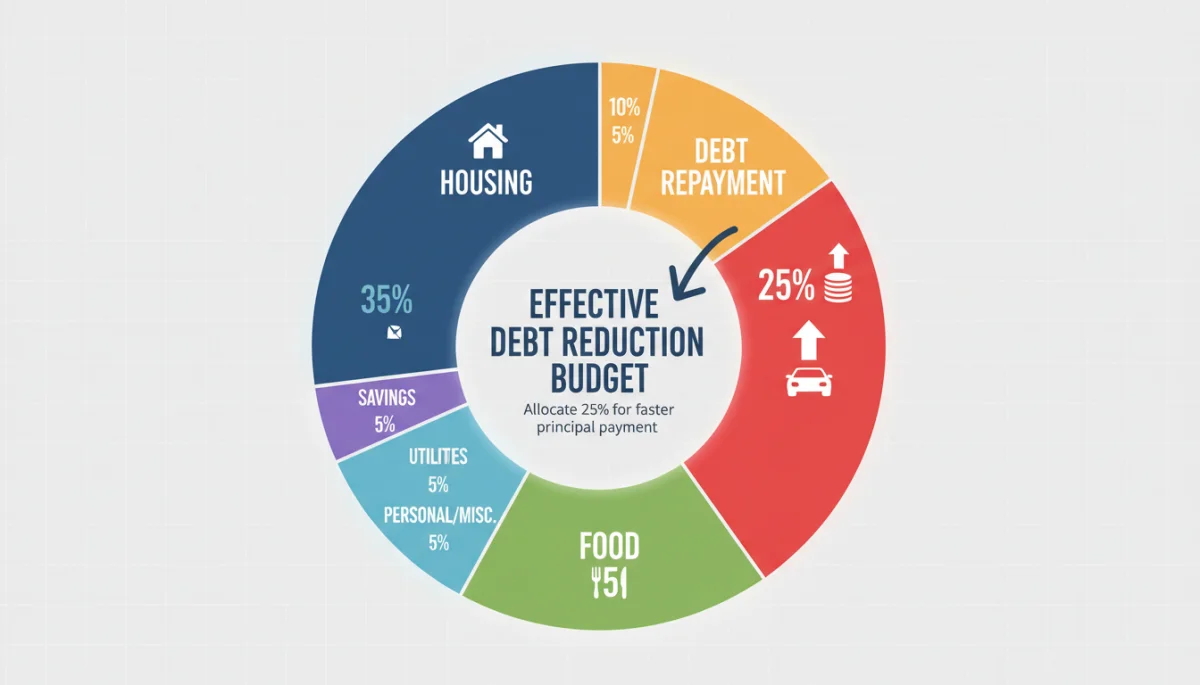
Your budget is the cornerstone of your debt repayment plan. It dictates how much money comes in and where every dollar goes. A realistic budget ensures you have enough for necessities while allocating a substantial portion towards debt. Be honest about your spending habits and identify areas where you can trim expenses without sacrificing your basic needs.
Setting clear financial goals
Beyond just paying off the $5,000, what are your broader financial goals? Perhaps it’s building an emergency fund, saving for a down payment, or investing for retirement. Aligning your debt repayment with these larger goals can provide additional motivation and perspective.
- Debt repayment target: Specify the exact amount to pay each month to reach $5,000 in 18 months.
- Emergency fund: Aim to save at least one month’s worth of expenses to prevent future reliance on credit cards.
- Long-term savings: Integrate a small amount of savings, even while paying off debt, to build good habits.
By meticulously crafting your personal finance plan, you transform an overwhelming goal into a series of manageable steps, making your journey to debt freedom feel achievable and empowering.
Implementing Effective Debt Repayment Strategies
Once your strategic personal finance plan is in place, the next crucial step is to implement effective debt repayment strategies. These methods are designed to accelerate your debt payoff, minimize interest accrual, and keep you motivated throughout the 18-month journey. Choosing the right strategy depends on your financial personality and the specifics of your debt.
There are several well-known approaches to debt repayment, each with its own advantages. Understanding these strategies will enable you to select the one that best fits your situation and provides the highest chance of success. Consistency in applying your chosen method is paramount.
The debt snowball method
This method involves paying off your smallest debt first, regardless of interest rate, while making minimum payments on all other debts. Once the smallest debt is paid, you take the money you were paying on it and add it to the payment of the next smallest debt. This creates a ‘snowball’ effect, building momentum and motivation.
The debt avalanche method
In contrast, the debt avalanche method prioritizes paying off the debt with the highest interest rate first, while making minimum payments on all other debts. This approach is mathematically more efficient, as it minimizes the total amount of interest paid over time.
- Snowball benefits: Psychological wins, quick motivation.
- Avalanche benefits: Saves most money on interest, financially optimal.
- Balance transfer cards: Consider transferring high-interest balances to a card with a 0% introductory APR, but be wary of fees and ensure you can pay it off before the promotional period ends.
Regardless of the method you choose, the key is to dedicate extra funds to your credit card debt beyond the minimum payments. Every extra dollar makes a significant difference in reducing your principal faster.
Maximizing Your Income and Minimizing Expenses
To accelerate your debt payoff, a two-pronged approach is often most effective: increasing your income and aggressively minimizing your expenses. While your budget helps allocate your existing funds, actively seeking ways to boost your earnings and cut costs can dramatically shorten your repayment timeline and free up more capital for your debt.
This section explores practical ways to enhance your financial capacity. It’s not just about deprivation; it’s about making smart choices that align with your goal of becoming debt-free. Every dollar saved or earned can be directly applied to your $5,000 credit card debt.
Exploring side hustles and additional income streams
Many opportunities exist to earn extra money outside of your primary job. Consider leveraging your skills, hobbies, or available time to generate additional income. This could range from freelancing and gig work to selling unused items or even taking on a part-time job.
Aggressively cutting unnecessary expenses
Review your budget with a critical eye, looking for areas where you can cut back without significantly impacting your quality of life. Small, consistent savings can add up quickly. Challenge every expense and ask yourself if it’s truly essential for your 18-month debt payoff goal.
- Evaluate subscriptions: Cancel unused streaming services, gym memberships, or app subscriptions.
- Reduce dining out: Cook more meals at home and pack lunches.
- Shop smarter: Look for sales, use coupons, and buy generic brands.
- Transportation costs: Consider carpooling, public transport, or walking/biking for shorter distances.
By actively pursuing both income maximization and expense minimization, you create a powerful financial engine that propels you faster towards paying off your credit card debt within the targeted 18 months.
Maintaining Motivation and Avoiding New Debt
The journey to becoming debt-free is a marathon, not a sprint. Maintaining motivation and, crucially, avoiding new debt are essential for the 18-month plan to succeed. It’s easy to get discouraged or fall back into old spending habits, especially when faced with unexpected expenses or tempting purchases. This section focuses on strategies to stay committed and vigilant.
Building new financial habits takes time and discipline. It requires a conscious effort to resist the allure of instant gratification and to prioritize your long-term financial health. Developing a strong mindset and having contingency plans in place will be vital for your success.
Celebrating small victories
Acknowledge and celebrate your progress along the way. Paying off a small balance, reaching a specific savings milestone, or simply sticking to your budget for a month are all reasons to celebrate. These small victories reinforce positive behavior and keep your spirits high.
Building an emergency fund
One of the most effective ways to avoid new debt is to build a robust emergency fund. This fund acts as a financial safety net, allowing you to cover unexpected expenses—like medical bills or car repairs—without resorting to your credit cards. Aim for at least 3-6 months’ worth of living expenses if possible, even if you start small.
- Automate payments: Set up automatic payments to ensure you never miss a due date and incur late fees.
- Unsubscribe from marketing emails: Reduce temptation by limiting exposure to sales and promotions.
- Find accountability: Share your goals with a trusted friend or family member, or join an online community for support.
- Review progress regularly: Periodically check your debt balance and budget to see how far you’ve come and make adjustments as needed.
By actively managing your motivation and fortifying your financial defenses against new debt, you significantly increase your chances of successfully paying off your $5,000 credit card debt within 18 months and establishing healthier financial habits for life.
Looking Beyond Debt: Building Financial Resilience
Successfully paying off $5,000 in credit card debt within 18 months is a remarkable achievement, but the journey doesn’t end there. The true victory lies in leveraging this experience to build lasting financial resilience. This means establishing habits and systems that prevent future debt accumulation and foster long-term financial security. It’s about transforming a temporary challenge into a permanent improvement in your financial life.
The lessons learned during your debt repayment period—disciplined budgeting, strategic saving, and mindful spending—are invaluable. This final section focuses on how to carry these positive changes forward, ensuring you maintain financial health and pursue new financial goals with confidence.
Continuing smart financial habits
Don’t abandon your budget or expense tracking once your debt is gone. Instead, repurpose these tools to manage your newfound cash flow. Redirect the money you were using for debt payments towards savings, investments, or other financial priorities. The discipline you developed is a powerful asset.
Investing in your future
With credit card debt out of the way, you have more capacity to invest in your future. Consider contributing more to your retirement accounts, opening a brokerage account, or saving for major life events like a home purchase or your children’s education. Financial resilience is built on proactive planning and consistent investment in your future self.
- Automate savings: Set up automatic transfers from your checking to your savings and investment accounts.
- Regular financial reviews: Schedule quarterly or annual financial check-ups to assess your progress and adjust your plan.
- Continue learning: Stay informed about personal finance topics to make educated decisions about your money.
- Avoid lifestyle creep: As your income potentially grows, resist the urge to increase your spending proportionally. Maintain a lean lifestyle to maximize savings and investments.
By consciously building financial resilience, you ensure that your efforts to pay off credit card debt lead to a sustainable and prosperous financial future, free from the burdens of high-interest debt and ready for new opportunities.
| Key Strategy | Brief Description |
|---|---|
| Strategic Budgeting | Create a detailed budget to track income and expenses, identifying areas for savings. |
| Debt Repayment Method | Choose between the debt snowball or avalanche method for efficient payoff. |
| Increase Income/Cut Expenses | Actively seek side hustles and aggressively reduce discretionary spending. |
| Build Emergency Fund | Establish a safety net to avoid new debt from unexpected costs. |
Frequently asked questions about credit card debt
The first step is to assess your current financial situation by calculating your net income and meticulously tracking all your expenses. This provides a clear picture of where your money goes and identifies areas for potential savings to allocate towards debt repayment.
The debt avalanche method saves more money on interest by prioritizing debts with the highest interest rates. The debt snowball method provides psychological wins by paying off smaller debts first, which can help maintain motivation. The ‘better’ method depends on your personal preference and financial habits.
To avoid new debt, build a robust emergency fund to cover unexpected expenses. Also, stick to a strict budget, cut unnecessary spending, and consider unsubscribing from marketing emails to reduce temptation. Developing financial discipline is key to long-term success.
If you can only afford minimum payments, focus on finding ways to increase your income through side hustles or reducing non-essential expenses. Even a small additional amount can make a significant difference over time due to the power of compounding interest on your debt.
Rebuilding credit after paying off debt can take several months to a few years. Factors include the severity of previous credit issues and consistent responsible financial behavior afterward. Maintaining low credit utilization and making all payments on time are crucial for improving your credit score.
Conclusion
Paying off $5,000 in credit card debt within 18 months is an ambitious yet entirely achievable goal with the right strategic personal finance plan. By understanding the true costs of debt, diligently assessing your financial situation, crafting a realistic budget, and implementing effective repayment strategies, you can systematically dismantle your debt. Moreover, by maximizing your income, minimizing expenses, and maintaining unwavering motivation, you not only eliminate current debt but also build a foundation for lasting financial resilience. The journey requires discipline and commitment, but the reward of financial freedom and peace of mind is immeasurable.
